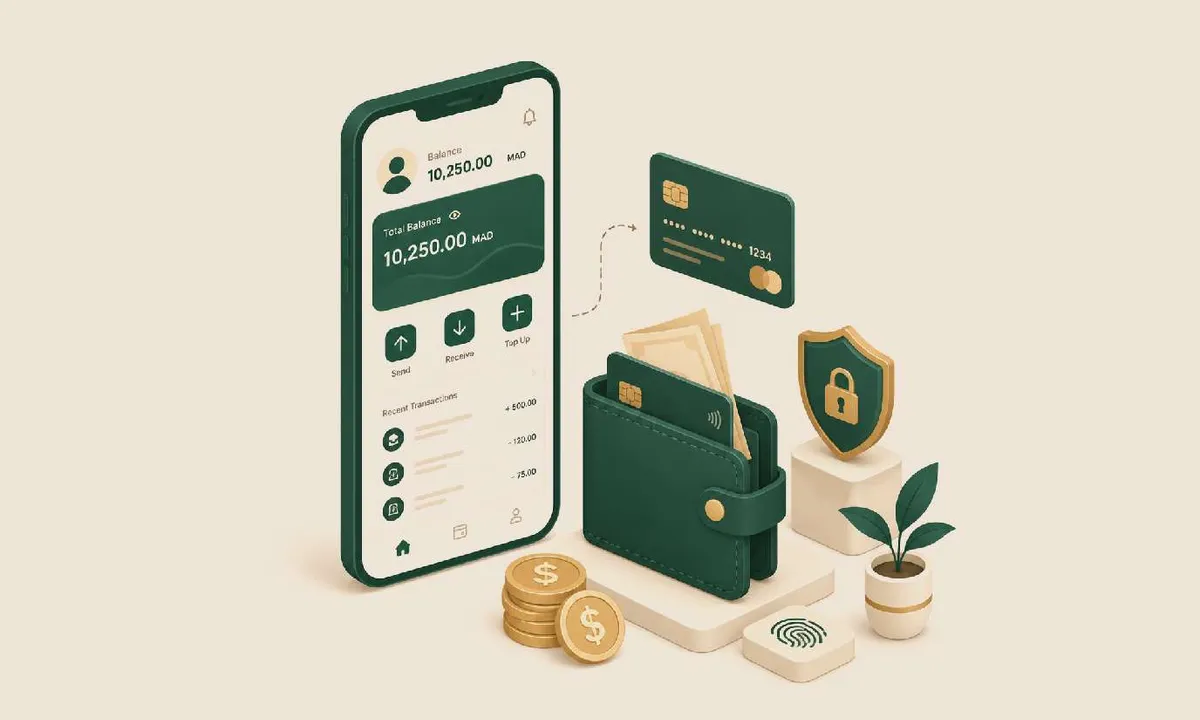
Saudi Arabia has rapidly transformed into a cashless society, with digital payments now exceeding hundreds of billions of riyals annually. Apps like STC Pay and urpay have forever changed the way people pay and transfer money, opening the door to massive investment opportunities in digital wallets. But a digital wallet isn’t just any app: it’s a strictly regulated financial product that requires high security and compliance with Central Bank (SAMA) regulations. Those who build them correctly enter a massive market, while those who neglect security and compliance risk their entire venture. With Nasq4, we build them for you—secure and compliant—using custom code that you fully own.
1. Why has developing an e-wallet become a promising opportunity in Saudi Arabia?
The Kingdom is undergoing a rapid digital financial transformation driven by Vision 2030 and society’s shift toward cashless payments. With the growth of e-commerce and the culture of digital payments, the digital wallet has become a promising investment opportunity:
Digital wallets are no longer the exclusive domain of telecom companies and banks; they have become an opportunity for entrepreneurs and companies to build specialized payment solutions—whether an in-app wallet, a loyalty program, or a payment platform for a specific sector. The key is to build them on a solid foundation of security and compliance.
2. Types of Wallets and Regulatory Considerations (A Critical Point)
First and foremost, you must understand your wallet type and its regulatory requirements, as this will determine the entire course of your project. Not every wallet requires a license:
🎁
Loyalty Wallet
Points and rewards within your app—no SAMA license required.
🛒
Closed Wallet
Balance used only within your platform—often no license required.
🔄
P2P Wallet
Peer-to-peer transfers — requires a license from the Central Bank (SAMA).
🏦
Full-featured wallet
Withdrawals, deposits, and transfers — requires full regulatory compliance.
Very important note: Any wallet that holds or transfers customer funds (P2P) requires a license from the central bank (SAMA). Loyalty wallets and closed wallets within your app, however, often do not require a license. We’ll help you clearly identify your wallet type and its requirements before you start, so you won’t be caught off guard later.
3. Get to Know Nasq – Saudi Expertise in Financial Apps
In a Saudi market experiencing rapid digital transformation, Nasq stands out as a specialist in digital business solutions, building fully customized, highly secure applications tailored to sensitive financial products. We follow a clear methodology: Analysis – Planning – Design – Implementation. Our core services include:
Since e-wallets are part of the broader world of mobile apps, you can learn more about our comprehensive services on our Mobile App Design Company in Saudi Arabia page.
4. Key Features of a Digital Wallet
There are features that serve as the cornerstone of any successful digital wallet, and their absence makes the experience incomplete:
💳
Balance and Top-Up
Top up the wallet from cards or a bank account.
🔄
Instant Transfers
Send and receive money between users.
🧾
Bill Payment
Pay bills and services (SADAD integration).
📱
QR Code Payments
Make quick payments in stores by scanning a QR code.
💰
Link Cards
Link your Mada, Visa, and Mastercard cards.
🎁
Offers and Rewards
Points and discounts that encourage use.
📊
Transaction History
Track all transactions with transparency.
🔔
Instant Notifications
Alerts for every payment or transfer.
🔐
Secure Authentication
Fingerprint, facial recognition, and PIN for login and transactions.
🏧
Withdrawals and Deposits
Transfer funds to a bank account (depending on the account type).
🌐
Arabic and English
Bilingual interface.
🖥️
Control Panel
User and transaction management.
5. Security and Compliance (SAMA – PCI-DSS – KYC)
An e-wallet is a financial product, and security is not a feature but a prerequisite. Any vulnerability means a loss of funds, trust, and reputation. Therefore, we build the wallet based on the highest security and compliance standards:
🏛️
SAMA Compliance
Compliance with the Central Bank’s requirements based on the type of wallet.
🛡️
PCI-DSS Standard
Protecting card data in accordance with global standards.
🆔
Know Your Customer (KYC)
Verifying user identities in accordance with regulations.
🚫
Anti-Money Laundering (AML)
Monitoring of suspicious transactions and money laundering.
🔒
Strong Encryption
Encrypting data and transactions in transit and at rest.
📝
Audit logs
Complete tracking of every transaction to protect both parties.
Why does this matter? Security and compliance are what distinguish a trusted wallet from a risky venture. We build your wallet to financial industry standards from the ground up and guide you toward the correct regulatory path based on its type, protecting both your business and your users.
6. Integration with Financial and Payment Systems
The strength of a wallet lies in its integration with the Saudi financial ecosystem. An isolated wallet is limited, while an integrated one offers a seamless experience:
- Licensed payment gateways: Integration with SAMA-approved gateways for secure payment processing.
- SADAD system: Integration for paying bills and government services.
- Saudi Network (Mada): Connection to the most widely used Mada cards and accounts.
- Banks: Connect to bank accounts for deposits and withdrawals.
- APIs: Flexible integration with payment systems and other services.
7. User and Admin Dashboards
The wallet serves two parties, and each has its own tools:
User App
- Create an account and verify identity
- Top up balance
- Transfer funds between users
- Pay with QR codes in stores
- Paying Bills and Services
- Link bank cards
- Transaction History
- Instant Notifications
- Offers and Rewards
- Secure Fingerprint Authentication
Administration Dashboard
- User and Account Management
- Real-time Transaction Monitoring
- Know Your Customer (KYC)
- Suspicious Activity Monitoring
- Commission and Fee Management
- Detailed Financial Reports
- Promotions and Rewards Management
- Setting Limits and Permissions
- Audit logs
- Support and Troubleshooting
8. Profit Models for Digital Wallets
The e-wallet is a profitable digital venture with multiple revenue streams that convert transactions into recurring revenue:
💰
Transaction Fees
A small percentage on certain transfers or transactions.
🏪
Merchant Fees
A commission on payments made through the e-wallet at stores.
📢
Sponsored Offers
Partnerships with stores for exclusive offers within the wallet.
💎
Premium Services
Benefits or higher limits with a paid subscription.
🧾
Service Fees
Fees for paying bills or for certain services.
📊
Merchant Analytics
Paid data and services for partner merchants.
9. Technical Infrastructure and Custom Code
The wallet handles funds and sensitive financial data, so a ready-made template with vulnerabilities is not suitable. That’s why we build with custom code that ensures the highest security and performance:
- Financial-grade security: Protection built into the foundation, not added as an afterthought.
- High performance: Fast transaction processing even during peak times.
- Scalability: An architecture that accommodates growth in users and transactions.
- Custom code, not off-the-shelf: Tailored to your wallet type and regulatory requirements.
- Full ownership: You receive the code and the database, so you’re never at anyone’s mercy.
10. How do you choose a reliable company to design a digital wallet in Saudi Arabia?
A digital wallet is a sensitive financial product, so choosing a development company is a critical decision that must be based on security and financial expertise:
- Ensure they have experience with financial applications and high-level security.
- Make sure they understand the regulatory aspects (SAMA) and can guide you in the right direction.
- Make sure it adheres to security standards (PCI-DSS, KYC, AML, encryption).
- Choose a company that builds with custom code and grants you full ownership.
- Most importantly: Transparency in explaining regulatory requirements before you start, not after.